What Happens After You Apply for a Mortgage in Colorado
Quick version: you submitted your application, and then nothing happened for a few days, and now you're wondering if someone lost your file. Nobody lost it. There's a sequence running in the background, and almost none of it produces an email. Here's what's inside: what shows up in the first three days, what underwriting is actually doing, why they ask for the same document twice, what genuinely slows a Colorado file down, and the two deadlines the law gives you.
The quiet part is the normal part
The hardest stretch of getting a mortgage isn't the paperwork. It's the silence after the paperwork.
You spent a weekend gathering pay stubs and bank statements, you hit submit, and then your inbox went still. That's not a bad sign. Most of what happens next happens to your file, not to you, and files don't send updates.
What follows is the order things usually run in. Every file is a little different, and your lender may sequence a step or two differently, but this is the shape of it.
Day one to three: your loan estimate shows up
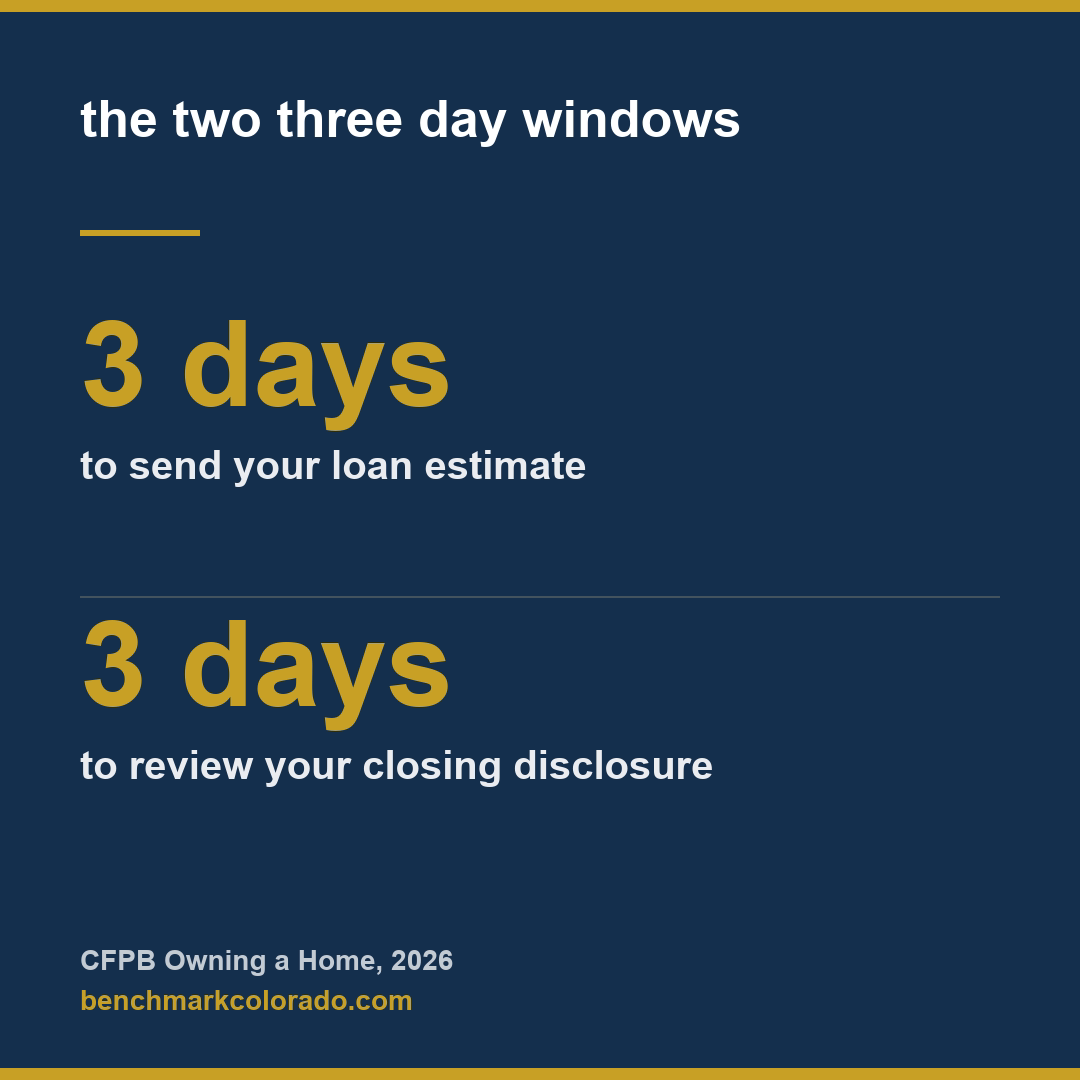
Within three business days of a completed application, your lender is required to send you a loan estimate.
It's a standardized three-page form, and every lender's version looks the same on purpose, so you can put two side by side and actually compare them. The CFPB's loan estimate explainer walks through it page by page.
Read page one. That's where your estimated monthly payment, your interest rate, and whether that rate is locked all live.
If a number on it surprises you, ask about it that week, not the week of closing. Estimates are estimates, and some of the costs on that form can move before you sign.
Your file goes to underwriting
Underwriting is a person reading your file and deciding whether the loan makes sense on paper.
They're checking four buckets, roughly: your income, your assets, your credit, and the property itself. Not your character, not how badly you want the house. Four buckets.
That review takes time because it's genuinely detailed. Someone is tying your deposits to your income, matching your job history to your pay stubs, and reading your credit report line by line.
Underwriting decides, and nobody can promise you an outcome before they do. Not your loan officer, not your agent. What we can do is make the file as clean as possible going in.
The appraisal gets ordered
Somewhere in this stretch, an appraisal is ordered on the property.
An appraiser visits the home and gives an opinion of value, which the lender uses to make sure the loan amount makes sense for what's being bought. This is a separate track from your income review, and it runs on its own clock.
In Colorado mountain country, this step is often the one that stretches. There are fewer appraisers covering large areas, fewer recent comparable sales in places like Teller and Gunnison counties, and winter access can complicate a site visit.
If you're buying above the Front Range, build a little extra runway into your contract dates. It's easier to ask for it up front than to renegotiate later. We go deeper on that in our writing on how mountain property appraisals work in Colorado.
Conditions: the part nobody warns you about
After the first review, underwriting sends back a list of conditions. This is normal. It is not a rejection.
A condition is a request for something else before the loan can move forward. Common ones include:
- A letter of explanation for a deposit, a credit inquiry, or a gap in employment
- Updated documents, because pay stubs and bank statements go stale after a certain point
- Proof of homeowners insurance for the property
- Clarification on a debt that shows on your credit report differently than you described it
Almost every file gets a conditions list. A long one doesn't mean your loan is in trouble.
Turn them around fast, and the file moves fast. This is the single biggest lever you personally control in the whole process.
Why they ask for a document you already sent
This one frustrates people more than anything else, so it's worth explaining.
Sometimes the request is genuinely new: underwriting saw something in the first document that raised a second question. Sometimes the original expired, because most lenders want recent statements and pay stubs, and "recent" keeps moving while your file is open.
And sometimes a page was cut off, or an account number was cropped, or the download was a summary rather than the full statement.
Send the whole document, every page, including the blank ones. It sounds silly. It saves days.
Not sure whether your numbers even work for the house you're looking at? Take the two minute quiz and get a ballpark before you spend another weekend at open houses.
Clear to close, and the second three day window
When underwriting signs off on the conditions, your file is marked clear to close.
Then your closing disclosure goes out. It's a five page form that shows your final loan terms and closing costs, and you're entitled to receive it at least three business days before you sign. The CFPB's closing disclosure guide explains what to compare.
Use those three days. Put your loan estimate and your closing disclosure next to each other and check that the loan amount, the rate, the term, and the monthly payment match what you expected.
That three day window exists for you, and it isn't a formality. If something looks off, that's the moment to say so.
What actually slows a Colorado file down
In twenty plus years of doing this, the delays cluster in a handful of places, and credit scores are rarely the culprit.
- Insurance, especially in wildfire risk areas, where getting a bindable quote can take longer than people expect
- Appraisal timing in mountain and rural counties with thin comparable sales
- Slow condition responses, which is the one thing entirely in your hands
- New debt taken on mid process, like a car loan or a furniture financing offer
- Large unexplained deposits that need to be sourced and documented
- Well, septic, and access road items on unique properties
That last one is its own subject. If you're buying a cabin or an unusual parcel, our piece on financing a home with a well and septic system covers what gets inspected and when.
What to do while you wait
The most useful thing you can do during underwriting is keep your financial picture still.
That means: don't open new credit, don't finance a vehicle, don't move large sums between accounts without telling your loan officer first, and don't change jobs if you can help it. Every one of those can send your file back for another look.
Boring is the goal here. A file that looks the same on closing day as it did on application day is a file that closes on time.
If your situation changes anyway, tell your loan officer immediately. Almost everything is workable when we know about it early, and almost nothing is when we find out at the closing table.
The Colorado wrinkle
Statewide, Colorado files carry a few extras that surprise buyers moving in from elsewhere.
Mountain properties bring insurance questions, access questions, and sometimes water rights questions that a suburban file never touches. Second home purchases have their own requirements. And in resort communities, seasonal timing affects how quickly an appraiser can get out to the property.
None of that makes a loan harder to get. It just means the runway is longer, and knowing that in advance changes how you write your contract.
You shouldn't have to figure this out alone
The process after you apply isn't complicated so much as it's invisible. Once you can see the sequence, the quiet stretches stop feeling like something's gone wrong.
I've walked more than 12,000 Coloradans through this, and the ones who feel calm at closing are almost always the ones who knew what was coming. That's the whole trick. You can read what a few of them said about it in their reviews.
If you're earlier than that and just want a real number before you talk to anyone, find out where you'd likely land in about two minutes.
Diane Beaumont is Branch Manager and Loan Originator at Benchmark Mortgage Colorado, NMLS #247026. Licensed in CO, AZ, MT, FL. This article is for education only and is not a commitment to lend. Loan terms, timelines, and program requirements vary by lender, loan type, and individual circumstances.